Indian equities: resilience with opportunity in sight
India equities: potential for a turnaround as market leadership broadens
Indian equities had a difficult first half of 2026. Foreign participation was muted, reflecting the perception that India isn’t a direct beneficiary of the “AI trade”. At the same time, energy costs rose sharply and the Indian rupee weakened. Together, these factors drove one of the weakest half-year performances in recent memory—comparable in scale to the sell-offs seen during the 2008 Global Financial Crisis and the initial Covid-19 shock.
In the third quarter of 2026, however, the market narrative has started to shift. The sharp swings in AI-exposed assets that dominated the first half of the year are increasingly giving way to broader market leadership, as investors rotate away from a narrow group of AI winners and diversify their exposure. Against that backdrop, Indian equities have quietly begun to outperform. Earnings momentum is improving, macro and high-frequency indicators are firming, and foreign inflows are showing early signs of turning.
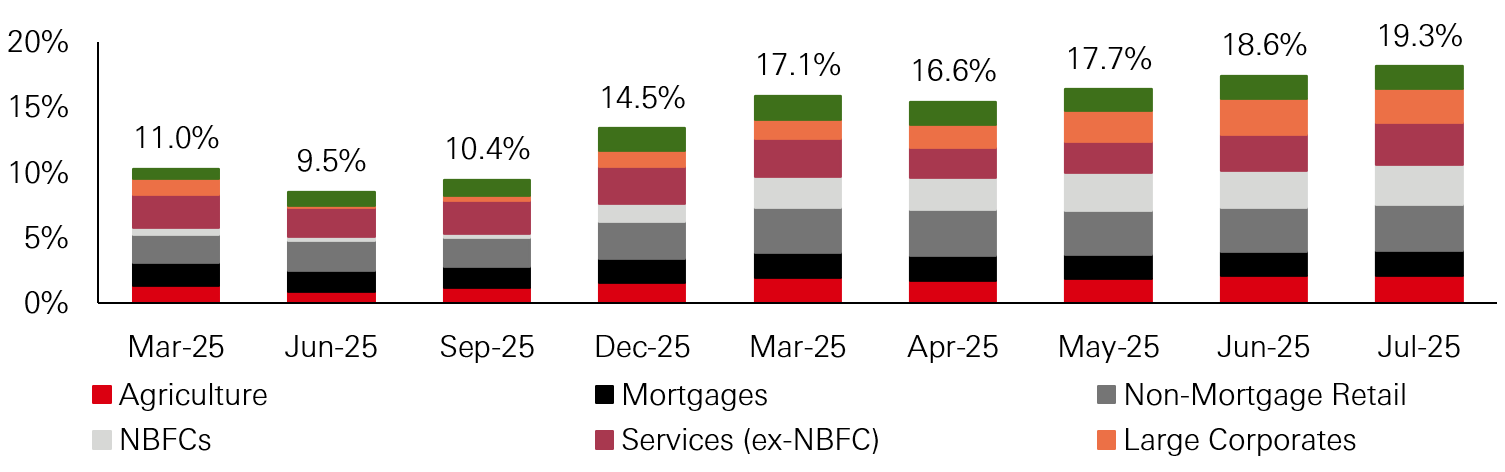
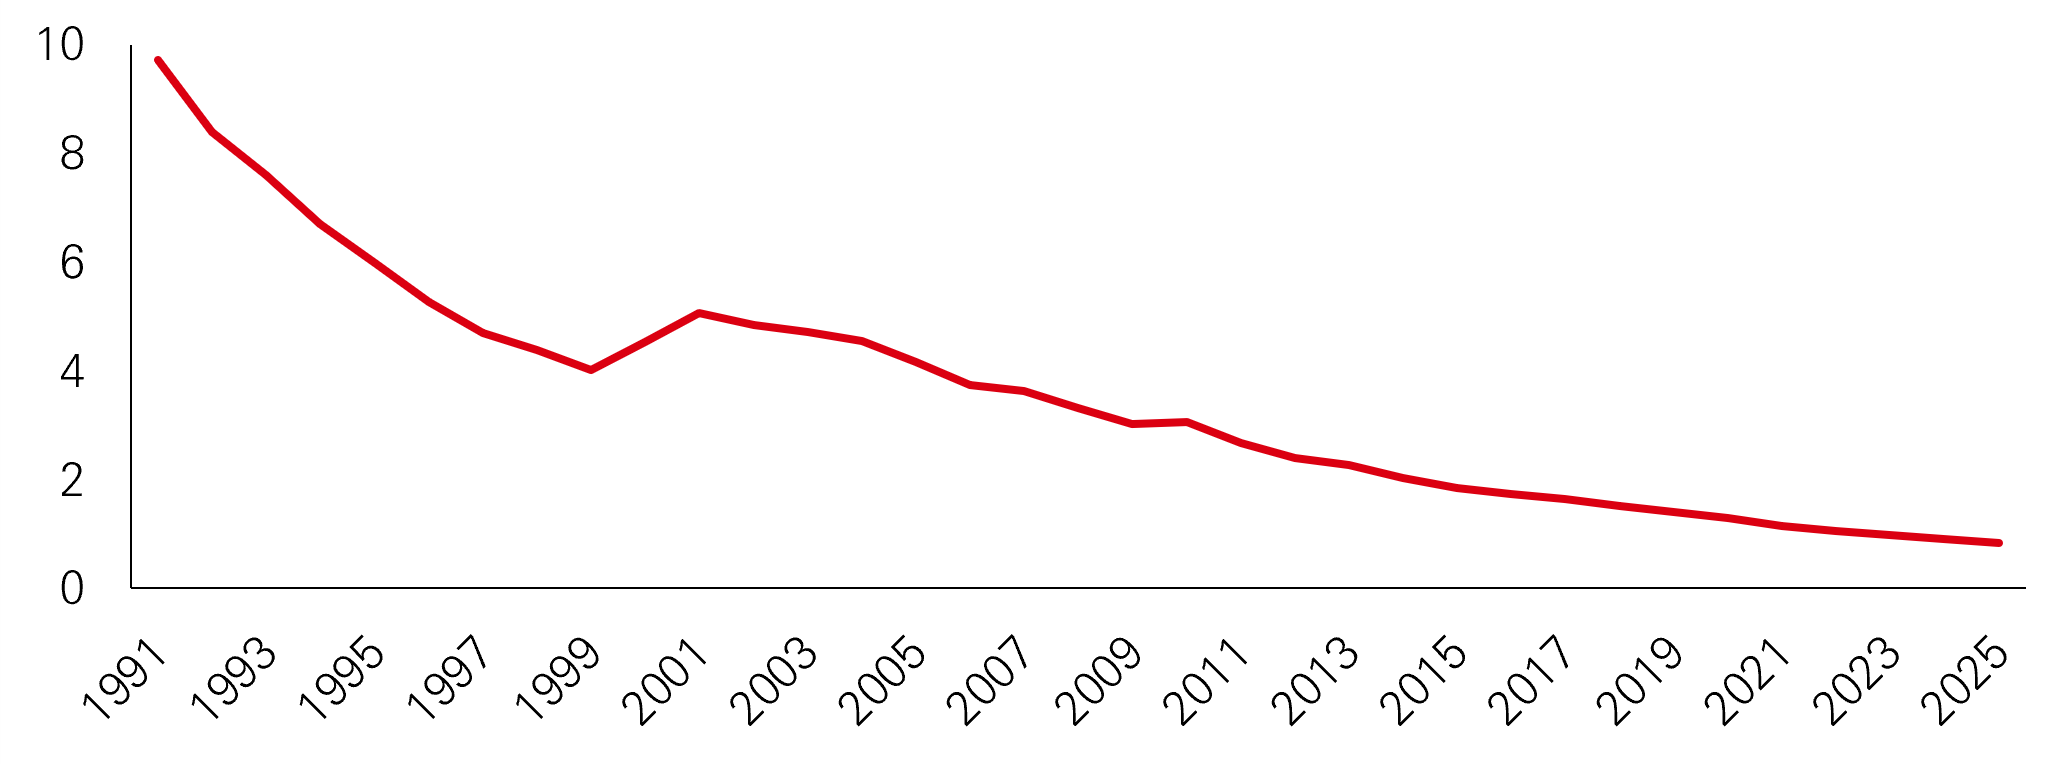
The main takeaway is that growth has remained more resilient than many expected, underpinned by policy support, sustained strong credit growth, and a structurally lower oil intensity than in previous cycles (Fig.1 and 2). Meanwhile, earnings momentum is picking up again, with both revenues and profits surprising to the upside. Positioning and flows are also becoming more constructive: inflows are turning while India remains under-owned relative to its index weight, creating scope for meaningful marginal inflows if broader risk sentiment stabilises. Finally, a steadier INR reduces the hurdle rate for global investors by limiting currency drag on USD-based returns.
Fig 1: India’s headline credit growth reaches a two-year high, led by NBFCs
Headline credit growth
Click the image to enlarge
NBFC stands for non-banking financial companies. Source: RBI, CEIC, Goldman Sachs Research, data as of July 2026
Source: HSBC Asset Management, August 2026.
This commentary has been produced by HSBC Asset Management to provide a high level overview of the recent economic and financial market environment, and is for information purposes only. The views expressed were held at the time of preparation; are subject to change without notice and may not reflect the views expressed in other HSBC Group communications or strategies. This marketing communication does not constitute investment advice or a recommendation to any reader of this content to buy or sell investments nor should it be regarded as investment research. The content has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. You should be aware that the value of any investment can go down as well as up and investors may not get back the amount originally invested. Furthermore, any investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in established markets. Any performance information shown refers to the past and should not be seen as an indication of future returns. You should always consider seeking professional advice when thinking about undertaking any form of investment.
Solid fundamentals despite the Middle East conflict
Growth resilience: reforms and policy support are showing through. Despite the energy price shock that followed the Middle East conflict in 1Q 2026, India’s GDP growth in 2Q 2026 printed at 7.8 per cent year-on-year, materially above expectations, with broad-based contributions from investment, exports and consumption. That outcome reinforces the view that India’s growth engine is proving relatively resilient, helped by a mix of near-term policy support and longer-running reform dividends that are increasingly visible in macro outcomes.
A key structural differentiator is India’s steadily declining oil intensity over the past three decades. Energy efficiency gains, greater electrification and a gradual shift towards less energy-intensive growth have reduced the economy’s sensitivity to oil price spikes, lowering the probability that an external energy shock translates into a prolonged domestic slowdown. In practical terms, this means the hurdle for an oil-driven growth scare is higher than it used to be, and periods of volatility may be more likely to create short-lived dislocations than lasting damage—particularly if reforms continue to lift productivity and policy remains oriented towards sustaining investment and domestic demand.
Fig 2: India’s oil consumption intensity has declined over time
Oil consumption intensity (Tonnes/INR mn)
Click the image to enlarge
Source: CEIC, Goldman Sachs Research, data as of December 2025
Fiscal policy has also been supportive. Income tax cuts and GST rate rationalisation implemented through 2025 were designed to raise household disposable incomes and strengthen consumption. These measures were complemented by fuel excise duty reductions and limited pass-through of higher energy prices, helping to cushion consumers. Demand has been further reinforced by robust government and public-sector capex, alongside bank credit growth of around 19 per cent—a two-year high—which is providing a meaningful tailwind to domestic activity.
Impact from monetary policy easing in 2025 is now showing up in the credit channel, with headline credit growth reaching a two-year high (Fig. 1). In addition to cutting rates by a cumulative 125bp in 2025, the Reserve Bank of India (RBI) introduced a broad set of regulatory relaxations aimed at lowering funding costs and easing banks’ capital constraints. Together, these measures are supporting credit creation and real economic activity. Importantly, inflation also appears contained despite higher commodity prices: headline inflation was 4.4 per cent in July—within the RBI’s target range—while core inflation remains moderate, giving policymakers room to prioritise growth without reopening inflation concerns.
Earnings are increasingly reflecting this macro improvement. NIFTY companies revenue growth in the latest reporting season (2Q 2026) was the strongest in 10 quarters while earnings growth of ~19 per cent came in meaningfully above expectations. High-frequency indicators, including credit demand and auto sales, continue to point to sustained momentum, reinforcing the case that the recovery is broadening rather than narrowing.
Foreign flows starting to turn
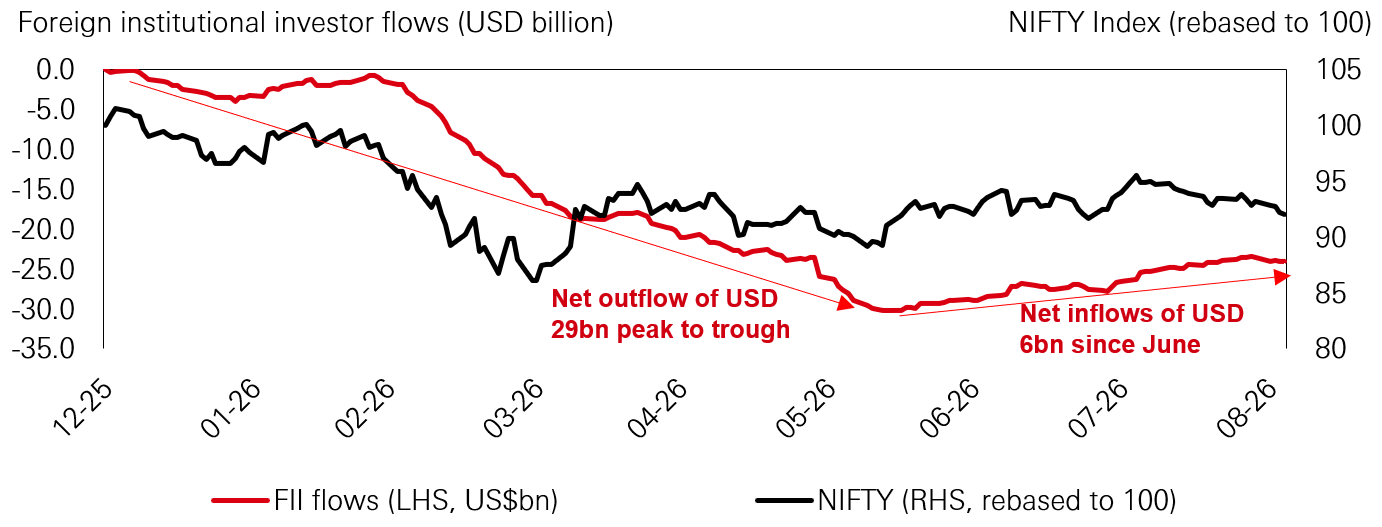
Flows are turning from de-risking to reallocation. With much of the recent AI-related de-risking already absorbed, investor attention is gradually shifting beyond a narrow set of US-led themes. India remains under-owned across many active global funds, so if broader risk sentiment stabilises, even modest reallocations could translate into meaningful marginal inflows—supporting market liquidity and, potentially, relative performance. Early evidence is emerging: foreign institutional investors (FIIs) have turned net buyers since mid-June, with more than USD 6bn of net inflows, compared with ~USD 29bn peak-to-trough net outflows in 1H 2026. In addition, Foreign Currency Non-Resident Bank (FCNR (B)) inflows have surprised to the upside, materially boosting FX reserves, reducing external vulnerability and supporting the banking system’s capacity to fund ongoing credit growth. A steadier rupee is also meaningful for global allocators, as it reduces currency drag on USD-based returns and lowers the hurdle rate for overseas investors—broadening participation beyond index heavyweights.
Under-owned EM opportunity: diversification with improving fundamentals. Geopolitics and US Fed policy remain key swing factors, but in an environment where volatility in AI-exposed sectors and markets remains elevated, Indian equities are looking more attractive for investors seeking diversification and long-term compounding. The mix is supportive: improving macro tailwinds and fundamentals provide an anchor, while strong domestic equity flows and inflecting foreign inflows add incremental support. In our view, the macro impulse remains constructive for positioning in Indian financials, real estate and consumer discretionary, where improving activity, credit dynamics and demand trends are likely to be most visible.
Fig 3: Foreign institutional inflows have started to return since mid-June
Click the image to enlarge
Source: HSBC Asset Management, as of September 2026.
Past performance does not predict future returns. Any forecast, projection or target contained in this presentation is for information purposes only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecasts, projections or targets. The views expressed above were held at the time of preparation and are subject to change without notice. The information provided does not constitute any investment recommendation or advice. Diversification does not ensure a profit or protect against loss. For illustrative purposes only.
Important information
For Professional Clients and intermediaries within countries and territories set out below; and for Institutional Investors and Financial Advisors in the US. This document should not be distributed to or relied upon by Retail clients/investors.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. The performance figures contained in this document relate to past performance, which should not be seen as an indication of future returns. Future returns will depend, inter alia, on market conditions, investment manager’s skill, risk level and fees. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries and territories with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries and territories in which they trade.
This document provides a high level overview of the recent economic environment. It is for marketing purposes and does not constitute investment research, investment advice nor a recommendation to any reader of this content to buy or sell investments. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination.
The contents of this document may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. All non-authorised reproduction or use of this document will be the responsibility of the user and may lead to legal proceedings. The material contained in this document is for general information purposes only and does not constitute advice or a recommendation to buy or sell investments. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. We do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed herein are those of HSBC Asset Management at the time of preparation and are subject to change at any time. These views may not necessarily indicate current portfolios' composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients' objectives, risk preferences, time horizon, and market liquidity. Foreign and emerging markets: investments in foreign markets involve risks such as currency rate fluctuations, potential differences in accounting and taxation policies, as well as possible political, economic, and market risks. These risks are heightened for investments in emerging markets which are also subject to greater illiquidity and volatility than developed foreign markets. This commentary is for information purposes only. It is a marketing communication and does not constitute investment advice or a recommendation to any reader of this content to buy or sell investments nor should it be regarded as investment research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. This document is not contractually binding nor are we required to provide this to you by any legislative provision.
All data from HSBC Asset Management unless otherwise specified. Any third-party information has been obtained from sources we believe to be reliable, but which we have not independently verified.
HSBC Asset Management is the brand name for the asset management business of HSBC Group, which includes the investment activities that may be provided through our local regulated entities. HSBC Asset Management is a group of companies in many countries and territories throughout the world that are engaged in investment advisory and fund management activities, which are ultimately owned by HSBC Holdings Plc. (HSBC Group).
- In Australia, this document is issued by HSBC Bank Australia Limited ABN 48 006 434 162, AFSL 232595, for HSBC Global Asset Management (Hong Kong) Limited ARBN 132 834 149 and HSBC Global Asset Management (UK) Limited ARBN 633 929 718. This document is for institutional investors only and is not available for distribution to retail clients (as defined under the Corporations Act). HSBC Global Asset Management (Hong Kong) Limited and HSBC Global Asset Management (UK) Limited are exempt from the requirement to hold an Australian financial services license under the Corporations Act in respect of the financial services they provide. HSBC Global Asset Management (Hong Kong) Limited is regulated by the Securities and Futures Commission of Hong Kong under the Hong Kong laws, which differ from Australian laws. HSBC Global Asset Management (UK) Limited is regulated by the Financial Conduct Authority of the United Kingdom and, for the avoidance of doubt, includes the Financial Services Authority of the United Kingdom as it was previously known before 1 April 2013, under the laws of the United Kingdom, which differ from Australian laws;
- In Bermuda, this document is issued by HSBC Global Asset Management (Bermuda) Limited, of 37 Front Street, Hamilton, Bermuda which is licensed to conduct investment business by the Bermuda Monetary Authority;
- In France, Belgium, Netherlands, Luxembourg, Portugal, Greece, Finland, Norway, Denmark, Spain and Sweden this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026);
- In Germany, this document is issued by HSBC Global Asset Management (Deutschland) GmbH which is regulated by BaFin (German clients) respective by the Austrian Financial Market Supervision FMA (Austrian clients);
- In Hong Kong, this document is issued by HSBC Global Asset Management (Hong Kong) Limited, which is regulated by the Securities and Futures Commission. This content has not been reviewed by the Securities and Futures Commission;
- In India, this document is issued by HSBC Asset Management (India) Pvt Ltd. which is regulated by the Securities and Exchange Board of India;
- In Italy, this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026), through its Italian branch, regulated by Banca d’Italia and Commissione Nazionale per le Società e la Borsa (Consob);
- In Japan, this document is issued by HSBC Asset Management (Japan) Ltd (JRN 3010001124868), regulated by the Financial Services Agency;
- In Malta, this document is issued by HSBC Global Asset Management (Malta) Limited which is regulated and licensed to conduct Investment Services by the Malta Financial Services Authority under the Investment Services Act;
- In Mexico, this document is issued by HSBC Global Asset Management (Mexico), SA de CV, Sociedad Operadora de Fondos de Inversión, Grupo Financiero HSBC which is regulated by Comisión Nacional Bancaria y de Valores;
- In the United Arab Emirates, this document is issued by HSBC Investment Funds (Luxembourg) S.A. – Dubai Branch (Level 20, HSBC Tower, PO Box 66, Downtown Dubai, United Arab Emirates) regulated by the Capital Market Authority (CMA) in the UAE to conduct investment fund management, portfolios management, fund administration activities (CMA Category 2 license No.20200000336) and promotion activities (CMA Category 5 license No.20200000327).
- In the United Arab Emirates, this document is issued by HSBC Global Asset Management MENA, a unit within HSBC Bank Middle East Limited, U.A.E Branch, PO Box 66 Dubai, UAE, regulated by the Central Bank of the U.A.E. and the Capital Market Authority in the UAE under CMA license number 602004 for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority. HSBC Bank Middle East Limited is a member of the HSBC Group and HSBC Global Asset Management MENA are marketing the relevant product only in a sub-distributing capacity on a principal-to-principal basis. HSBC Global Asset Management MENA may not be licensed under the laws of the recipient’s country of residence and therefore may not be subject to supervision of the local regulator in the recipient’s country of residence. One of more of the products and services of the manufacturer may not have been approved by or registered with the local regulator and the assets may be booked outside of the recipient’s country of residence.
- In Singapore, this document is issued by HSBC Global Asset Management (Singapore) Limited, which is regulated by the Monetary Authority of Singapore. The content in the document/video has not been reviewed by the Monetary Authority of Singapore;
- In Switzerland, this document is issued by HSBC Global Asset Management (Switzerland) AG. This document is intended for professional investor use only. For opting in and opting out according to FinSA, please refer to our website; if you wish to change your client categorization, please inform us. HSBC Global Asset Management (Switzerland) AG having its registered office at Gartenstrasse 26, PO Box, CH-8002 Zurich has a licence as an asset manager of collective investment schemes and as a representative of foreign collective investment schemes. Disputes regarding legal claims between the Client and HSBC Global Asset Management (Switzerland) AG can be settled by an ombudsman in mediation proceedings. HSBC Global Asset Management (Switzerland) AG is affiliated to the ombudsman FINOS having its registered address at Talstrasse 20, 8001 Zurich. There are general risks associated with financial instruments, please refer to the Swiss Banking Association (“SBA”) Brochure “Risks Involved in Trading in Financial Instruments”;
- In Taiwan, this document is issued by HSBC Global Asset Management (Taiwan) Limited which is regulated by the Financial Supervisory Commission R.O.C. (Taiwan);
- In Turkiye, this document is issued by HSBC Asset Management A.S. Turkiye (AMTU) which is regulated by Capital Markets Board of Turkiye. Any information here is not intended to distribute in any jurisdiction where AMTU does not have a right to. Any views here should not be perceived as investment advice, product/service offer and/or promise of income. Information given here might not be suitable for all investors and investors should be giving their own independent decisions. The investment information, comments and advice given herein are not part of investment advice activity. Investment advice services are provided by authorized institutions to persons and entities privately by considering their risk and return preferences, whereas the comments and advice included herein are of a general nature. Therefore, they may not fit your financial situation and risk and return preferences. For this reason, making an investment decision only by relying on the information given herein may not give rise to results that fit your expectations.
- In the UK, this document is issued by HSBC Global Asset Management (UK) Limited, which is authorised and regulated by the Financial Conduct Authority;
- In the US, this document is issued by HSBC Securities (USA) Inc., an HSBC broker dealer registered in the US with the Securities and Exchange Commission under the Securities Exchange Act of 1934. HSBC Securities (USA) Inc. is also a member of NYSE/FINRA/SIPC. HSBC Securities (USA) Inc. is not authorized by or registered with any other non-US regulatory authority. The contents of this document are confidential and may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose without prior written permission.
- In Chile, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Chilean inspections or regulations and are not covered by warranty of the Chilean state. Obtain information about the state guarantee to deposits at your bank or on www.cmfchile.cl;
- In Colombia, HSBC Bank USA NA has an authorized representative by the Superintendencia Financiera de Colombia (SFC) whereby its activities conform to the General Legal Financial System. SFC has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Colombia and is not for public distribution;
- In Costa Rica, the Fund and any other products or services referenced in this document are not registered with the Superintendencia General de Valores (“SUGEVAL”) and no regulator or government authority has reviewed this document, or the merits of the products and services referenced herein. This document is directed at and intended for institutional investors only.
- In Peru, HSBC Bank USA NA has an authorized representative by the Superintendencia de Banca y Seguros in Perú whereby its activities conform to the General Legal Financial System - Law No. 26702. Funds have not been registered before the Superintendencia del Mercado de Valores (SMV) and are being placed by means of a private offer. SMV has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Perú and is not for public distribution;
- In Uruguay, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Uruguayan inspections or regulations and are not covered by warranty of the Uruguayan state. Further information may be obtained about the state guarantee to deposits at your bank or on www.bcu.gub.uy.
Copyright © HSBC Global Asset Management Limited 2026. All rights reserved. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of HSBC Asset Management.
Content ID: D077863_v1.0; Expiry Date: 01.10.2027